Due to the abolition of Real Property Gain Tax, the liquidity of the property is greatly increase. what is the impact of such annoucement to the banking and financial institution?
Usually, common loan packages have two types. There are with minimum bonding period of 5 years and without bonding constraints. No doubt, the former offer a better rate which can get a leverage interest through the loan tenure. Without bonding contract, the interest rate will be higher. This is understandable as financial institution wanted to get profit through the loan offer.
Since property trading is getting more liquid and property buyer will prefer to take loan which without bonding period constraint, as this provides more freedom on settlement of loan.
In view of the situation, i think Banker is going to adjust or come out with a new package which will focus in NO BONDING loan package.
Keen to know how good the offer will be.
30 April, 2007
No Bonding Loan
10 October, 2006
Conditional Redrawal- Loan
Whenever you see the REDRAW facility stated in the loan packages, try to ask few questions to the banker to clarify certain thing as it may vary from one to another.
1. How many time of redrawal is allow?
For instance, Public Bank got one loan package which only allow 1 withdrawal per annual.
2. Charge of Redrawal.
Friends, Nothing is free, all administration work will not be free. It imposed certain charge on every redraw! It could be Rm 50 per withdrawal.
3. Limitation of Withdraw Amount
Don't think you can withdraw whatever amount as you like and don't be too naive to tell, because there is your money. No way, since you sign the loan agreement you are bond to it. Understand the amount for withdraw is allow, eg. Public Bank allow minimum Rm 5k per withdraw and subsequent multiple of Rm 1k. So in other word, if your advance payment is only RM 4,500. Then, sorry you don't allow to withdraw that portion of money.
4. Notice of Redraw
Recently, i found Citibank offer a very attractive package as their loan product can allow for whatever amount of withdrawal (advance payment) without any notice and charge. Usually, for those who required to withdraw money are used for emergency, what if you still need to serve 1 week notice or more. It is killing off, right?
5. Commencement of Redraw Facility
Most of the borrowers thought that the redraw facility is implemented upon the signing of loan agreement. Here, to advise you again to read carefully on the book thick agreement note or ask the banker if it is not clear.
For completed property, it should be no problem, but for under construction property, it is always a risk or wrong interpretation that the redraw facility is upon signing of loan agreement. Most of the bank only allow withdrawal upon full release of loan, as for them to earn back their targetted profit because usually they offer a very low interest under construction stage.
Understand better on what you have signed can lead you to a safer position.
09 October, 2006
Redraw Facility - Loan
In current market, most of the home loan packages are offering REDRAW facility. It is a good for borrowers as they can put in their extra money to offset the loan interest and principle to shorten the loan tenure, and in other sides, it also facilitates the withdrawal of any extra payment once the borrower need some money for emergency or any.
Here, what i would like to highlight is that, Loan Agreements are varied from banks to banks and the clauses insides have to be read through thoroughly, at least once. It will give you a better picture of how the condition and the facilities apply. Get banker to explain if you have any doubt, as this is their duty to explain any question raise under the agreement.
For under construction property, some of the banks allow for Prepayment and gives daily rest interest facility. However, it imposes a condition that NO WITHDRAW until fully release of loan. Take Note on this points, under construction period is about 24 months or 36 months, as this period no withdraw is allowed. To prevent any cash flow problem within this period, do spare some money on hand as to avoid the misinterpretation of REDRAW facility given.!!
06 October, 2006
Home Loan Calculation
Let's show the home loan calculation as it is different from car loan or others.
Loan Amount : RM 100,000.00
Interest Rate (p.a) : 6.50%
Installment (p.mth) : RM 800.00
The calculation flow of the first month installment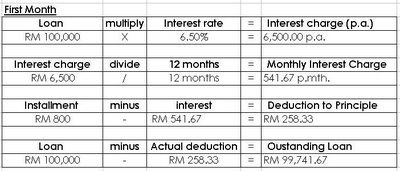
This is the second month of installment calculation,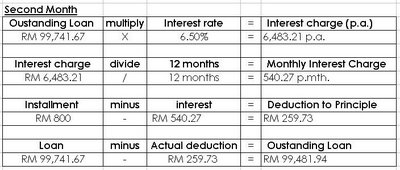 Then, the subsequent months will be follow with the above formula. When the outstanding loan become ZERO, there is the settlement of loan and total months of repayment is the whole loan tenure.
Hope it gives you a clear picture of how bank charge you on home loan.!
26 September, 2006
Home Loan Pitfall
Usually, most of the home loan packages in the market are having a minimum bonding period of 5 years. This is to protect bankers to earn back the expected revenue at the end of any early loan settlement from the borrower.
Of course, there are still some of the home loan packages which is NO Bonding Period constraint at all. No doubt such packages the interest rate will be higher.
The bonding period mostly is start from the date of full release of loan, but recently i notice some of the banks also offer to start calculate the bonding period from the date of first disbursement of loan.
Both packages are offering a good deal to borrower, however, the MAJOR difference here is the date of the commencement of bonding period. I am ok with the latter, but i have doubt on the former ( begin on the full release of loan ). For instance, under construction property usually it takes about 24/36 months, then plus 18 months for the last 2.5% of loan to be release at the expiry of defect liability period (after vacant possession issued). So it total up with 36 months + 18 months + 5 years (min bonding) = 9 years 6 months. Friend it is a decade of loan tenure before you can fully settle your loan without penalty, or looking for refinance.
This can make a huge difference and big gap in loan tenure, as refinance and help you to save up a big sum in interest and shorten your loan repayment.
Think twice and select carefully. Don't fall in this pitfall.!!
25 September, 2006
Source for Home Fund - HoMe Loan
A lot of people doesn't really understand their capability/affordability of purchasing a house. For instance, a house/ apartment which sells at Rm 100,000.oo, a layman will shout, " I don't have Rm 100,000.00, How to buy that property?!" why i call him as layman, cause only layman will give this kind of answer. Friend, there is always a legal clue that you can resolve this monetary issue, provided you know how, but of course definitely moaning at sky is not going to work!
Why i want to stress on "Legal" clue? Simply because illegal wise, you can rob a bank and like what newspaper shown recently grab the entire ATM, or with lesser risk - borrow money from "Ah Long" (Illegal Private bank or Financial Support Instituition with no gurantee, P & C for individual particular, no deposit, fast approval, etc - sound professional , right? but don't ever think of them, there will be a continuous nightmare for you, if you have selected them.) The best Option here i would like to recommend to you is BANK.
In fact, Bank is a legal option for you to loan your money. Then, a someone may ask which bank? Here, i tell you, any Bank will do, let 's me name a few for you, local bank will be Maybank, Public Bank, Hong Leong Bank, BumiPutra Commerce, Ambank, etc and Oversea bank will be Citibank, United Oversea Bank, HSBC, etc.
All the Banks above provide Home Loan Product to the consumer. Of course some of the term and condition need to be complied. Every bank has it own loan packages which are readily designed to suit for various range of consumer from poor to rich or from short term to long term.It depends on individual needs and accommodate to your financial status. Who know well on your financial position, ONLY yourself. So understand your own financial position and cash flow or even forecast your cash flow will help you to make a better choice in loan package selection.
Always remember, all banks are passionately welcoming to assist you in loan application as the loan department crew will explain all single detail to you while you approach them. What is the risk of making an enquiry at the bank? Police will not arrest you, you are not robber! Why want to risk your life and future, while there is a better channel awaiting for you. So Think out of the way, You can also own a House with a small little sum of money! May be only as little as 10% of the house price or even lesser, so stop moaning at the sky and visit my blog will let you know more. Find out more over here.
15 September, 2006
Base Lending Rate (BLR)
When you have decided to buy a property, most of you are rushing to look for a best deal of property loan packages to see which one suit you and save the most. In the market, there are plenty of home loan packages offer by all banks, some of them are Fixed rate or Term loan or Flexible mortgage..etc. Offers are keep changing from time to time.
Usually, you will notice that most of the packages in the market are offering BLR +/-of certain percentage (%). i believe most of the property buyer will have doubt on what is this BLR.
Base Lending Rate (BLR) is a minimum interest rate calculated by financial institutions based on a formula which takes into account the institutions' cost of funds and other administrative costs.
http://www.bankinginfo.com.my/index.php?ch=12&pg=26&ac=600#
The Interest Rate is computated from a complicated formula udner the control of bank malaysia. BLR is fixed and standardised in all banks. We can easily obtain the current BLR rate through any bank. For e.g. today 15th september 2006, BLR is 6.75%.
The BLR is a fluctuation rate. In other word, whatsoever loan packages under BLR +/-,is kind of rate that subject to market fluctuation. Therefore, some people would rather to choose fixed rate (normally is higher compare to others) because borrower can forecast their cash flow more accurately.
In fact, the selection of loan packages is preferably to include the possibility of fluctuation gap. It is to form a buffer to anticipate the increase of BLR. For short term loan, the risk of the fluctuation will be lesser compare to long term loan.
Honestly evaluate your own capability and the risk that you can absord, so it can help to select a better loan package to avoid ad hoc situation in future.


